Personal Finance Coach, PFC for short, holds the full state of my finances, checks every action against the plan's gates before it happens, and ranks every dollar's next-best use in one queue. The engineering docs are public. The source and the ledger never leave the machine.
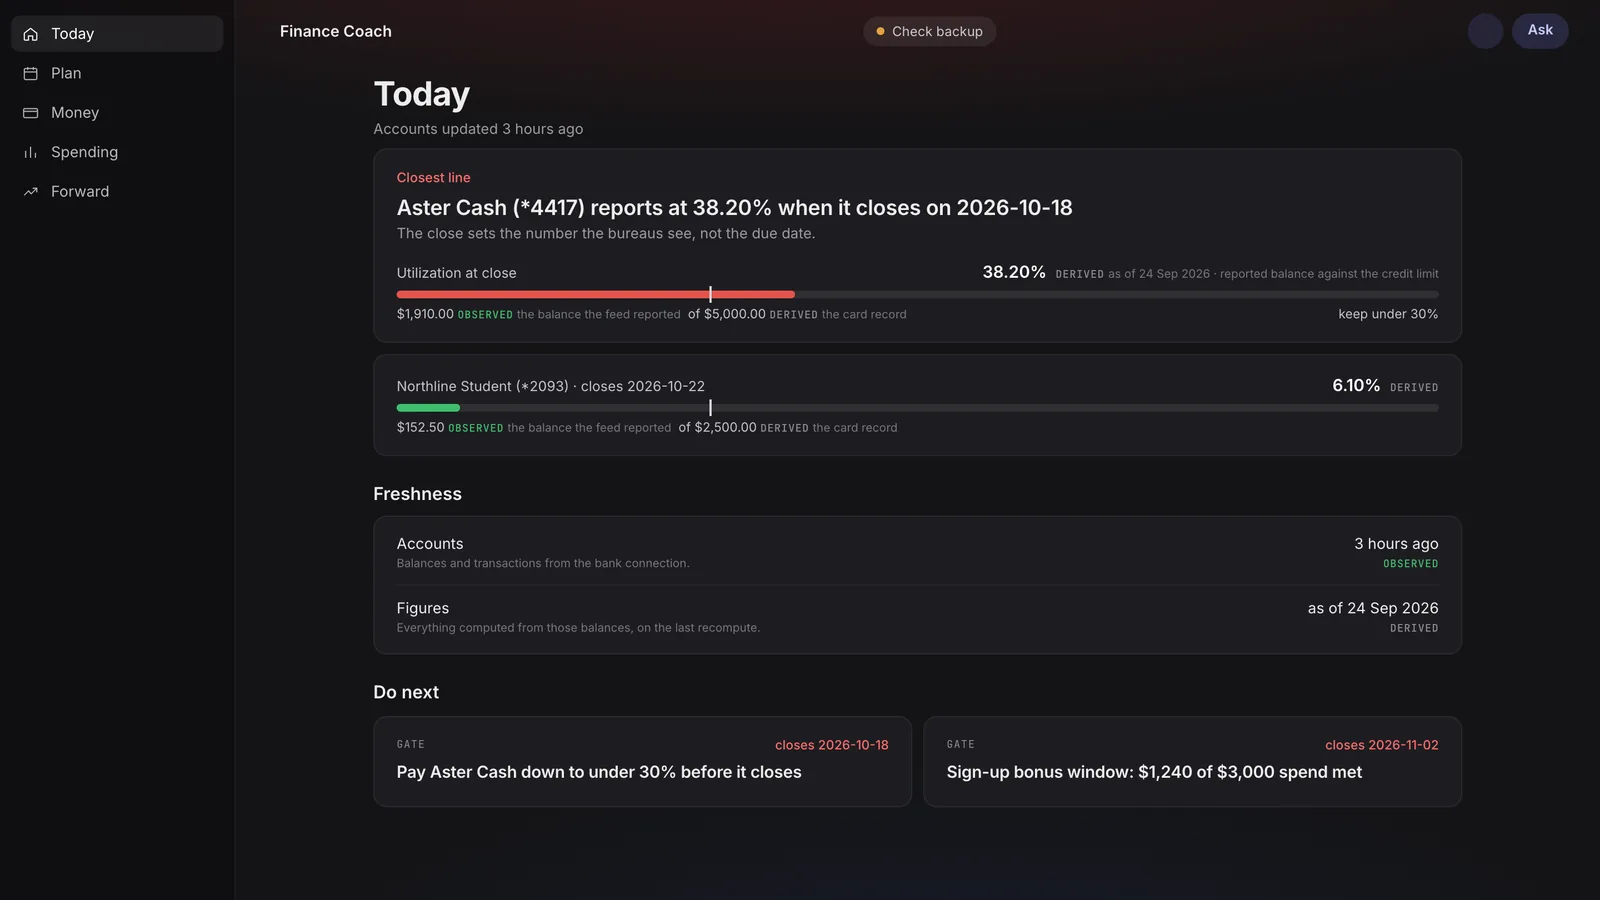
What it does
It is not a budgeting app. Budgeting is the solved part. The hard part is the credit-card meta-game and the sequencing decisions that no existing tool covers alongside a real financial model.
- Gates. Chase's 5/24 rule, per-card utilization at statement close, sign-up-bonus windows, annual-fee calendars, minimum account ages. Every action is checked against every gate before it happens.
- Points. Which card to use at which merchant, right now, given category caps already partly consumed this quarter.
- Opportunity cost. Every dollar has a next-best use. Idle cash, an unclaimed employer match, an uninvested contribution, a fee that should not exist: each is ranked in the same queue, in the same unit, as the card actions.
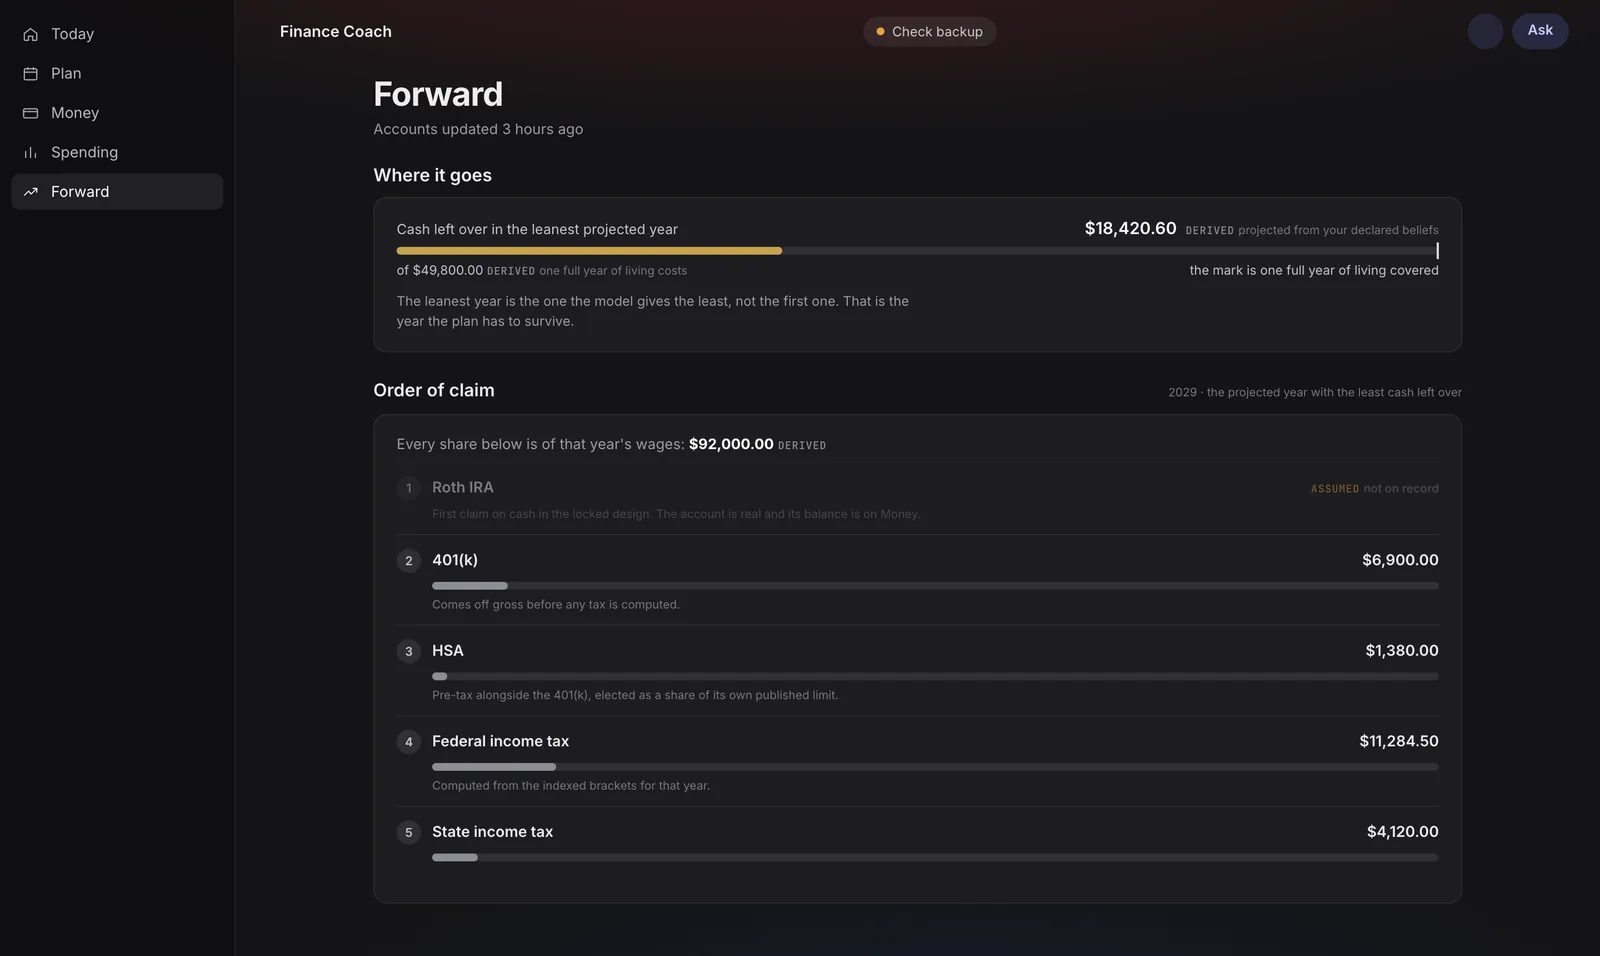
- Trajectory. A tax-aware five-year projection, frozen monthly and scored against what actually happens.
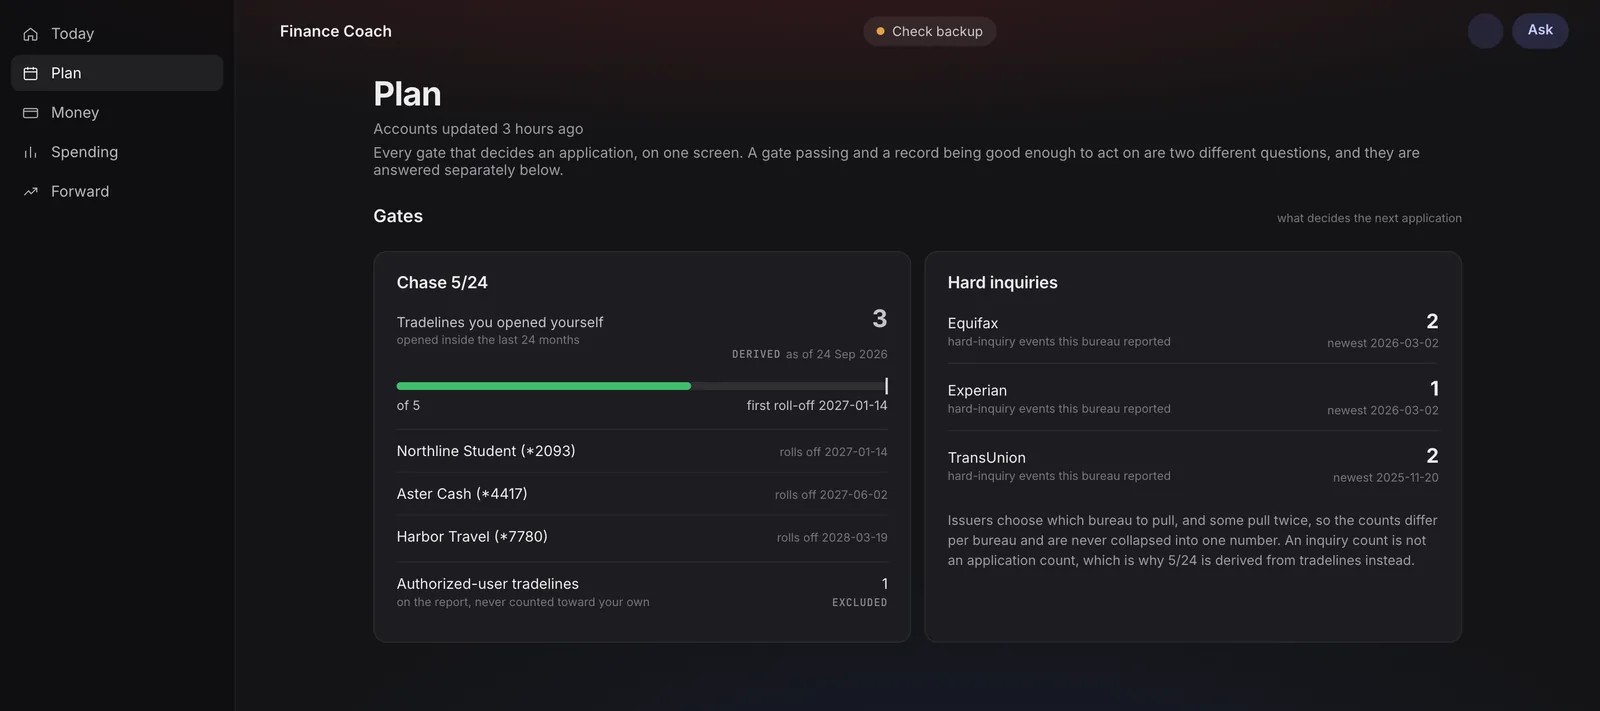
The one thing that cannot fail: never miss a gate. Everything else can degrade; this cannot.
Three constraints that shaped it
Plaid returns no merchant category code. The MCC is what determines points earned, and no consumer-accessible aggregator exposes it. So the merchant-to-bonus-category map is a table the system owns and improves, seeded from research and corrected from reconciliation drift. It is the single most valuable asset in the system; the bank connections are a commodity.
Fidelity is unreachable through Plaid. It shares data only through Akoya, which Plaid declines to integrate. Fidelity arrives through SimpleFIN Bridge instead, whose holdings support is undocumented. I verified it against my own account before building on it, and the ingest boundary re-validates the shape on every sync.
Nothing needs to be on the public internet. Poll on a timer instead of webhooks, request read-only products and never Plaid's auth product, and delegate access control to Cloudflare Access at the edge. A total token compromise reads history and cannot move money.
How it decides
The first engine was a rules layer: derive the credit file, check the gates, project the points, alert. The second replaced the objective function with opportunity cost across every dollar, evaluated over a versioned vector of assumptions.
Assumptions are first-class data. Hurdle rate, expected returns, future marginal tax outlook, value of time, risk posture: each is declared as a range rather than a point, stored append-only, and every derivation reruns when one changes. That is how the plan stays dynamic without a scraping loop or a chat history.
Every proposed action is compared against the alternative use of the same dollar across the whole declared range:
| Outcome | Behaviour |
|---|---|
| The difference has one sign across the entire range | Propose it |
| The sign flips inside the range | Escalate with both paths and the assumption that decides, naming the indifference point |
| The difference is under the materiality floor everywhere | Take the default silently and log it as immaterial |
Never pick silently on a close call.
The comparator bisects the assumption axis to find the indifference point rather than sampling it, and a narrowing step reports how much of the range the verdict depends on.
Twenty rules feed it, each a pure function over the derived state, each producing a ranked queue item in one unit: dollars of opportunity cost per year.
| Family | Rules |
|---|---|
| Card plan | SUB at risk · wrong card used · utilization before statement close · action breaks a gate · authorized-user tradeline closure |
| Cash | cash below the available rate · money-market fund vs invested |
| Employer | employer match unclaimed |
| Investments | expense-ratio alternative · uninvested contribution |
| Leakage | revolving interest · late fee · FX fee · maintenance fee · ATM or overdraft fee |
| Anomaly | outflow above baseline · new recurring charge · duplicate or unknown counterparty |
| Model health | assumption stale · tax-envelope breach |
The last family exists because the model's own inputs decay. Card terms change mid-plan without warning (one card in the plan was discontinued; another's annual fee roughly doubled over its lifetime), and tax parameters are indexed annually. Re-verification is a scheduled job with a provenance trail, not a memory.
Custody and safety
The failure mode is a financial mistake I cannot undo, so this is the part that got the most time.
- Writes are gated by provenance, not by surface. Three surfaces can propose a change. Every mutation carries an actor, and only six validated write tools exist on the MCP side. A model session can propose; it can never recompute or apply.
- The system of record is one SQLite file on an always-on VM, reached only through the tunnel. A startup assertion refuses to open a database inside a synced folder, because that failure mode is silent.
- The offsite backup is written with a key the host cannot use to delete. A compromised host can stop backups; it cannot destroy them. The restore drill is a CLI command that runs the same import-and-recompute path the fallback ingest exercises every day.
- Staleness is surfaced, not hidden. Every response carries an as-of time and the last successful sync. A freshness ladder fires per source, and a dead-man's switch fires when the timers stop.
What it taught me
Verification, not construction, is the binding constraint. The first five phases took six days. A 5/24-window bug then survived eleven plans and 446 passing tests, because every test encoded the same wrong assumption. Every phase now has to answer "how would I know this is wrong?" before it is planned, and the tax and projection engines are tested against a workbook built independently as a ground-truth oracle.
Patch rounds don't converge; redesigns do. One five-branch function needed four gap-closure rounds, each fix causing the next regression. What closed it was one consolidated pass with a total classification over the input space and a 125-cell enumerated acceptance table. That is now a repo hook: a third unpatched repair round on a phase is blocked at plan-write time.
"Missing capability" is usually a missing reader. Six of ten backlog items in one burn-down turned out to be capabilities that already existed: a ranked queue every reader discarded, a column no one read, a balance table with a writer and no reader.
Status
Milestone v1.0 shipped in August 2026: foundation, credit derivation and gates, the MCP server, statement and credit-report backfill, the merchant map, the live Plaid feed. Milestone v2.0, the wealth model, opened 13 August 2026 and shipped: versioned assumptions, the comparator, the twenty rules, the tax engine and projection. Three Plaid production items and one SimpleFIN connection sync daily on the host; the first frozen projection snapshot is in the production ledger, and its monthly scoring cannot be evaluated until snapshotted months elapse.
Since the public docs were written, the changes are about using it day to day rather than new math. "Which card" answers by merchant in one line, with the reasoning one tap away. A guard test reads every screen for machine vocabulary. A read-only MCP server, read-only by construction, lets Claude on claude.ai see the ledger: it verifies the Cloudflare Access token at the origin and refuses to start without the gate. A card's product change now keeps its account id instead of opening a new account.
As of 8 October 2026: 1,567 commits since 6 August 2026, 43 migrations, 327 test files and 3,229 unit tests, with Playwright checks across four viewports. The public docs date from September and lag these numbers.